


When a storm hits and damages your roof, dealing with your insurance company can feel overwhelming. We’ve put together some information to help you through the process of making residential roof insurance claims. Working with a local roofer can make a big difference, and we’ll explain how that partnership can help you get the repairs you need.
Key Takeaways
- Gathering good evidence of the storm damage to your roof is the first step in making a residential roof insurance claim. Photos and notes are important.
- Understand your insurance policy. Knowing what your coverage includes for roof damage helps when you file your residential roof insurance claims.
- A local roofer can help you assess the damage, work with your insurance adjuster, and make sure the repairs are done right.
Understanding Your Residential Roof Insurance Claims Process
When a storm hits and your roof takes a beating, the insurance claim process can feel overwhelming. We’re here to help you get through it. It’s important to know the steps involved so you can get your home repaired properly.
Documenting Storm Damage for Your Claim
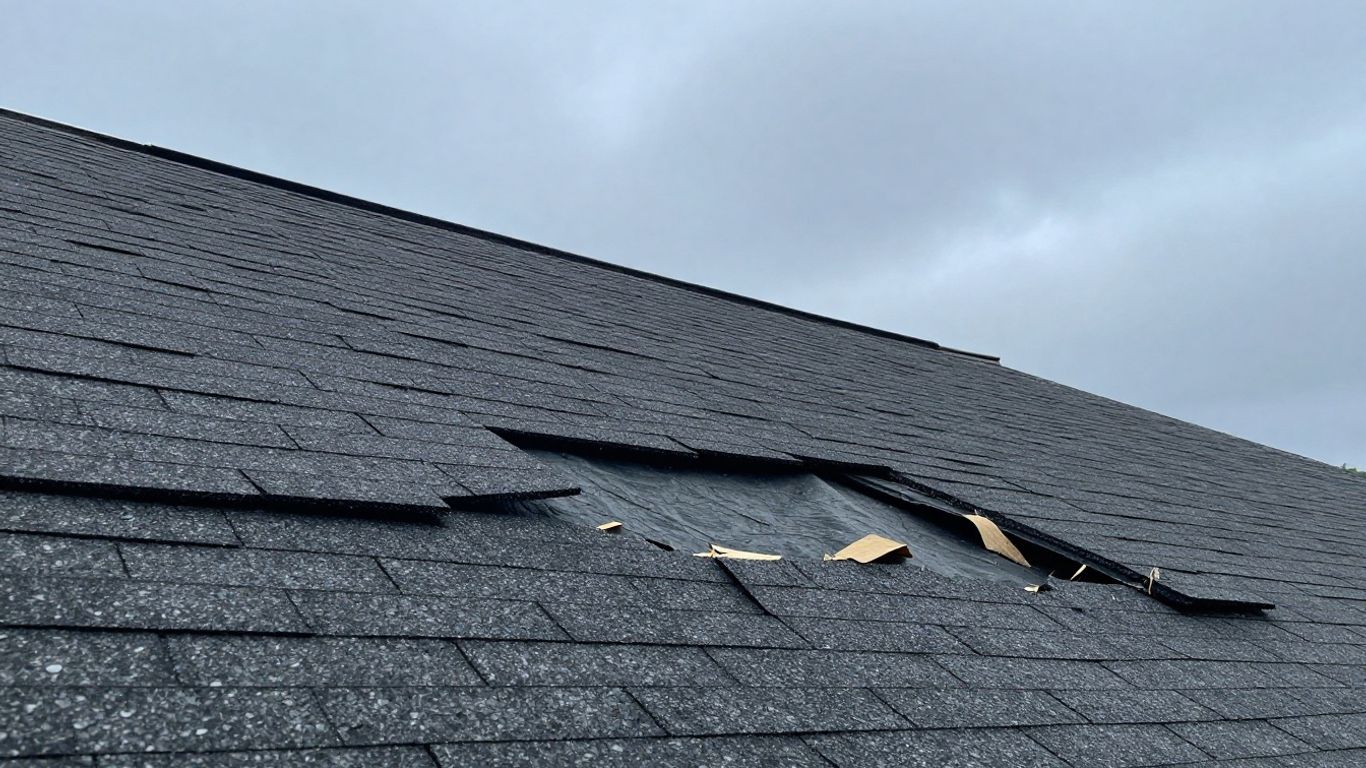
After the storm passes, the very first thing you should do is document any damage you see. Don’t touch anything if you can help it; just take pictures and videos. Get close-ups of any missing shingles, dents, or other visible problems. Also, take wider shots showing the overall condition of the roof and any debris that might have fallen on it. If there’s damage inside your home, like water stains on the ceiling or walls, document that too. This visual evidence is key to a successful claim.
Here’s a quick checklist for documenting:
- Take photos of the roof from the ground, if safe.
- Photograph any visible damage to shingles, flashing, or gutters.
- Document interior damage, such as water leaks or ceiling stains.
- Note the date and time you took the pictures.
Navigating Policy Details for Roof Coverage
Your homeowner’s insurance policy is a dense document, and understanding what it covers regarding roof damage can be tricky. Most policies cover damage from sudden events like windstorms and hail, but there are often limits and deductibles. You’ll want to look for sections that discuss "perils" covered and any exclusions. Pay close attention to your deductible, which is the amount you’ll have to pay out-of-pocket before the insurance company starts paying. Some policies might have specific limits for roof repairs or replacements, or they might cover it based on the roof’s age and condition.
It’s a good idea to read your policy before you need it. Knowing your coverage limits and what’s excluded can save a lot of headaches later on. If anything is unclear, don’t hesitate to call your insurance agent for clarification.
Here are some common policy terms to look out for:
- Actual Cash Value (ACV): This pays for the replacement cost of the damaged item minus depreciation (how much it has aged).
- Replacement Cost Value (RCV): This pays the cost to repair or replace the damaged item with a similar new item, without deducting for depreciation.
- Deductible: The amount you pay before your insurance coverage begins.
Partnering With A Local Roofer For Your Claim
Choosing The Right Roofing Professional
When storm damage hits, the first thing we often think about is getting the roof fixed. But before you call just anyone, it’s smart to pick a roofer who knows their way around insurance claims. We want someone local because they’re familiar with our area’s building codes and common storm issues. Plus, they’re usually quicker to respond. Look for roofers who have good reviews and have been in business for a while. Ask them if they have experience working with insurance companies on storm damage claims. A good roofer will be transparent about their process and won’t ask for a huge upfront payment before work begins.
Working With Your Roofer To File The Claim
Once you’ve chosen a roofer, they become a key part of your claim. They can help document the damage in a way the insurance company understands. This usually involves a detailed inspection report, photos, and sometimes even videos of the damage. They can also help you understand what your policy covers regarding roof repairs or replacement. It’s a good idea to have your roofer meet with the insurance adjuster when they come to inspect the damage. This way, both parties can discuss the extent of the damage together.
Here’s what we typically expect from a roofer during this stage:
- A thorough inspection of your roof and property for all storm-related damage.
- A detailed estimate outlining the necessary repairs or replacement.
- Assistance in communicating with your insurance company.
- Guidance on navigating the insurance claim process.
We find that having a roofer involved early on makes the whole claim process smoother. They speak the language of insurance and construction, which can be a big help when dealing with adjusters and getting the repairs done right.
Maximizing Your Residential Roof Insurance Claims Settlement
After the initial shock of storm damage, getting a fair settlement from your insurance company is the next big hurdle. We’ve found that being prepared and working smartly with your roofer makes a huge difference. It’s not just about getting the roof fixed; it’s about getting it fixed right and getting the compensation you deserve.
Negotiating With The Insurance Adjuster
This is where things can get a bit tense. The insurance adjuster works for the company, and their job is to assess the damage and determine the payout. We’ve learned that it’s best to have your chosen roofer present during the adjuster’s inspection. They speak the same language and can point out damage that might be missed or downplayed. Don’t be afraid to ask questions about their assessment. If you disagree with their findings, you have the right to present your own evidence. This could include photos, videos, and a detailed estimate from your roofer.
Here’s a typical breakdown of what happens:
- Initial Inspection: The adjuster visits your property.
- Damage Assessment: They document what they see.
- Estimate Review: They create their own repair estimate.
- Settlement Offer: They present you with an offer based on their findings.
If their offer seems low, don’t just accept it. We’ve seen cases where initial offers didn’t cover the full cost of proper repairs. Your roofer’s estimate, based on their experience with similar storm damage, becomes your counter-argument.
Understanding Approved Repairs And Replacements
Once you have an agreed-upon settlement, it’s important to know what it covers. Insurance policies often have different terms for repairs versus full replacement. Sometimes, they might offer to repair a section of the roof, but a good roofer can explain why a full replacement might be necessary due to the extent of the damage or the age of the roof. We always advise homeowners to get a clear explanation of the scope of work covered by the settlement.
- Repair vs. Replacement: Understand the policy’s stance on each.
- Matching Materials: If only part of the roof is replaced, the new materials should match the existing ones in color and type, if possible. Your policy might have specific language about this.
- Code Upgrades: Sometimes, local building codes require upgrades during roof work. Your policy may or may not cover these additional costs, so it’s good to clarify this upfront.
It’s vital to get everything in writing. Verbal agreements can lead to misunderstandings later on. Make sure the final settlement details clearly outline what repairs or replacements are covered and what materials will be used.
We’ve found that having a clear plan and a knowledgeable roofer by our side makes the whole process much smoother. It helps us get the best possible outcome for our homes after a storm.
Wrapping Up Your Storm Damage Claim
Dealing with storm damage to your roof can feel overwhelming, and then adding an insurance claim on top of that? It’s a lot. But by working with a local roofer who knows the process, we can make things much smoother. They’ve seen it all before and can help us get the repairs we need done right. Remember, don’t hesitate to ask questions and keep good records. It’s about getting your home back in shape after the storm passes.
Frequently Asked Questions
What’s the first thing we should do after a storm damages our roof?
After a big storm hits, our very first step should be to carefully check our roof for any obvious damage. We’ll want to take pictures or videos of anything we find, like missing shingles or dents. This documentation is super important for our insurance claim later on.
How can a local roofer help us with our insurance claim?
A local roofer is a great partner to have. They know roofs inside and out and can help us figure out exactly what needs fixing. They can also help us talk to the insurance company, making sure they understand the full extent of the damage and that we get a fair amount for the repairs.
What if the insurance company doesn’t offer enough money to fix our roof?
Sometimes, the first offer from the insurance company might not cover all the costs. If this happens, we’ll work with our roofer to review their assessment. They can help us explain to the insurance adjuster why more money might be needed, perhaps by providing extra evidence or a more detailed repair estimate to get a better settlement.
